A lower monthly repayment can make a new car feel more affordable, but it may come with a longer loan term or a larger final payment. The real comparison is the whole commitment, not one figure on a screen. The right vehicle finance solutions for new car buyers should fit the car’s drive-away price, your budget and how long you plan to own it.
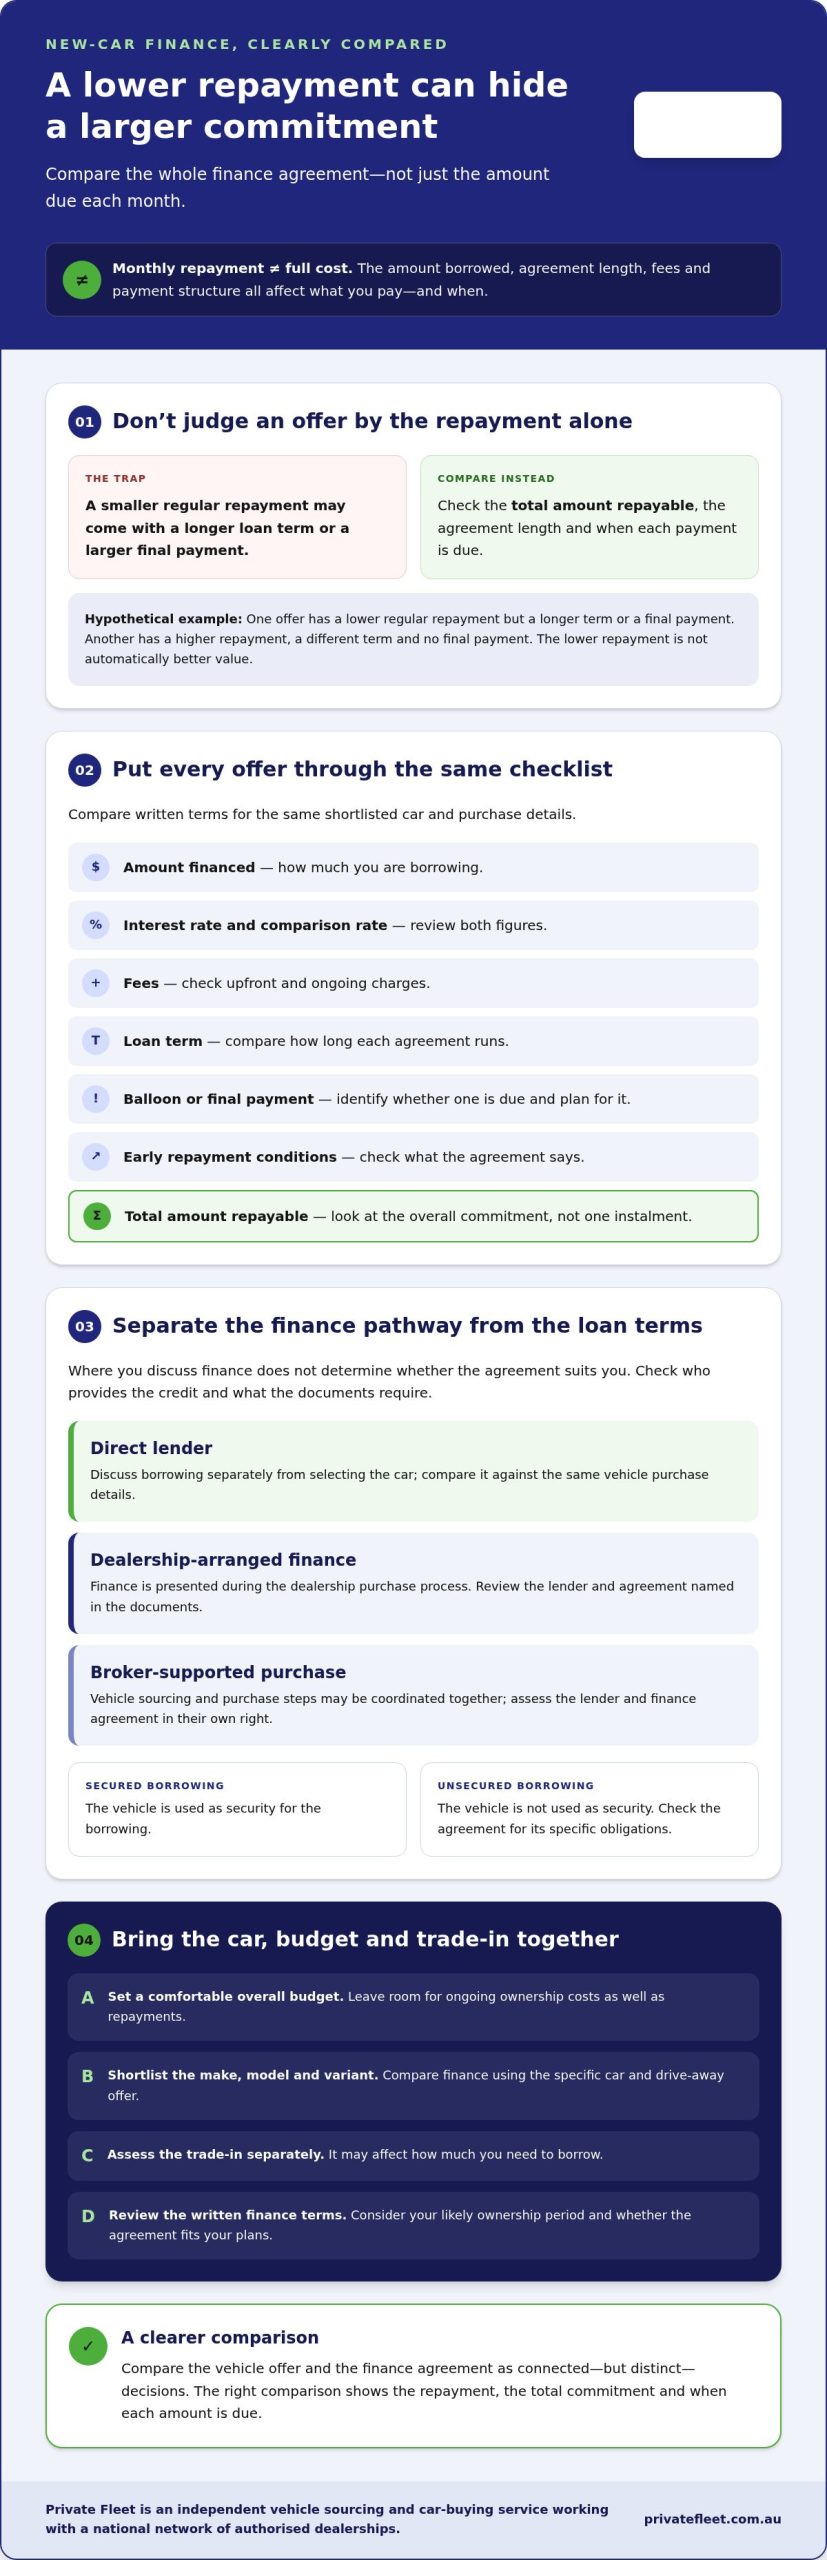
It’s understandable to focus on what you’ll pay each month, especially when offers use different rates, fees and repayment structures. To compare them clearly, look at the interest and comparison rates, loan term, upfront and ongoing fees, total amount repayable, and any final payment or early repayment conditions.
This guide explains the key points to weigh up, so you can assess repayments alongside the total borrowing and your ownership plans. It also looks at how your preferred car, trade-in and finance can be considered together. Private Fleet is an independent vehicle sourcing and car-buying service that works with a national network of authorised dealerships. Its tender process invites multiple dealers to compete for your business, while trade-in assistance and car finance can form part of the new-car purchase process.
Key Takeaways
- Compare lender finance with finance arranged through a dealership by looking at how each fits your new-car purchase, not by assuming one pathway is always better.
- Use a side-by-side checklist for vehicle finance solutions for new car buyers, including the amount financed, interest rate, comparison rate, fees and loan term.
- Check whether the agreement includes a balloon or final payment, and factor it into your plan rather than judging affordability by repayments alone.
- Set your budget, shortlist a car, review written finance terms and assess your trade-in as connected parts of the buying decision.
- See how vehicle sourcing, dealer tenders, trade-in assistance and finance can be coordinated through Private Fleet’s new-car buying process.
Why vehicle finance belongs in your new-car decision, not just your monthly budget
Compare finance alongside the vehicle and its drive-away offer. Vehicle finance is funding used to purchase a car, with the repayment terms set out in the relevant agreement. The car you choose affects how much you need to borrow, while the finance terms affect what that choice means for your budget over time. Looking at both together gives you a clearer basis for deciding.
It helps to keep three decisions distinct: which car and variant suit your needs, which finance agreement fits your finances, and what to do with your current vehicle if you have one to trade in. They still interact. A trade-in may affect the amount you need to borrow, and a different variant or purchase offer can change the amount financed. Compare the figures on the same basis, rather than treating a repayment in isolation as the cost of the car.
What should new-car buyers decide before comparing finance?
Start with a comfortable overall budget and a realistic repayment range. Leave room in your household budget for ongoing ownership costs, not just the loan repayment. Think about how long you expect to keep the car, your likely annual kilometres and whether your needs may change, such as regular regional trips or carrying more passengers.
Then shortlist the make, model and variant that meet those needs. Comparing finance before settling on the vehicle can mean weighing offers based on different cars, prices or inclusions. The general overview of car finance explains common ways a car purchase can be funded, but your comparison should centre on the specific written terms offered for your shortlisted new car.
Why is the repayment not the full picture?
A repayment reflects more than the interest rate. The amount borrowed, agreement length, fees and payment structure can all affect the amount due at each instalment and the total commitment. If an agreement includes a balloon or other final payment, consider that separately: a smaller regular repayment can leave a substantial amount to pay at the end.
Hypothetical example: Imagine two offers for the same shortlisted vehicle. One shows a lower regular repayment, but runs for longer or includes a final payment. The other has a higher repayment but a different term and no final payment. The first offer isn’t automatically better value. Compare the written terms, including the total amount repayable and when each payment is due.
That’s the practical value of comparing vehicle finance solutions for new car buyers as part of the purchase decision. You can assess whether the car, drive-away offer and agreement work together, instead of choosing an appealing repayment and discovering that the term or final payment doesn’t suit your plans. Keep the vehicle shortlist, finance comparison and trade-in assessment separate enough to judge clearly, then bring them together before committing.
Compare vehicle finance solutions by structure, term and purchase pathway
Compare how finance is presented as well as the agreement itself. The purchase pathway describes where the finance conversation takes place; the loan structure describes the arrangement set out in the contract. Neither label determines whether an offer suits you. Focus on who provides the credit, what the agreement requires and how the process fits your new-car purchase.
Finance pathway
Direct lender: You discuss borrowing separately from selecting the car. This can make it easier to keep the finance conversation distinct from the vehicle offer, provided you compare both against the same purchase details.
Dealership-arranged finance: Finance is presented during the dealership purchase process. Review the lender and agreement named in the documents, then assess the finance terms independently of the car offer.
Broker-supported purchase: A broker can help coordinate vehicle sourcing and purchase steps, with finance considered as part of the wider process. The lender and agreement remain important to assess in their own right.
These are ways of arranging or discussing finance, not guarantees of particular terms. A useful Australian reference is the Moneysmart.gov.au car loan guide, which outlines considerations for comparing car loans. Use it for general guidance, then rely on the current written offer and agreement for the details that apply to your purchase.
How do secured and unsecured borrowing differ?
A secured loan uses the vehicle as security for the borrowing; an unsecured loan does not. The agreement sets out the specific obligations and consequences, so check its wording rather than relying on the label alone. Consider how the structure fits your circumstances and compare the full terms. The government car-loan guidance can help clarify general differences.
How does finance fit with a dealer or broker purchase pathway?
A dealership may discuss finance while you’re considering a vehicle, while a broker-supported process can bring sourcing and purchase coordination into the same conversation. Either way, keep the vehicle offer and finance agreement clear as separate documents and decisions. Understanding how the car-buying process works can help you see where vehicle sourcing and purchase steps fit.
As you compare vehicle finance solutions for new car buyers, note who the lender is, which agreement applies and how finance relates to the specific vehicle purchase. If you’d like to discuss your new-car requirements, share your preferred make or model, postcode and buying timeframe.
Look beyond repayments: a checklist for comparing new-car finance offers
Put each offer beside the same vehicle and purchase details before comparing finance. Use the same make, model, variant, drive-away price, deposit and trade-in assumptions. If one quote uses a different price basis or amount borrowed, its repayment may not be a fair comparison.
Record the details from each written offer in a table. This makes differences easier to spot and gives you a clear list of terms to check in the agreement.
| What to compare | What to record |
|---|---|
| Amount financed | The amount borrowed after accounting for the deposit and any trade-in contribution. |
| Interest rate | The stated rate and whether the agreement describes it as fixed or variable. |
| Comparison rate | The disclosed comparison rate, plus the assumptions or exclusions attached to it. |
| Fees | Each upfront or ongoing fee shown in the offer and agreement. |
| Loan term | The length of the agreement and the number and frequency of repayments. |
| Final payment | Any balloon or other amount due at the end, listed separately from regular repayments. |
Which finance figures deserve a like-for-like comparison?
The interest rate is the rate used to calculate interest under the agreement. The comparison rate combines the interest rate with most upfront and ongoing fees to give a broader indication of borrowing cost. It may not reflect every fee or suit every loan amount and term, so read its assumptions and exclusions. Check current Australian disclosures and lender terms before relying on a quoted figure.
Fees and the loan term can affect the total amount payable, even when two offers show similar rates. A longer term may spread repayments over more time, but compare the full agreement rather than inferring overall value from the instalment alone. Don’t treat an advertised rate as a personalised offer. Use the figures in the current written terms.
What should you check about the agreement’s end point?
Look for a balloon or other final payment, and note when it falls due and how it changes the amount you’ll need to pay over the agreement. If you plan to sell or trade in the car before the term ends, check the contract for relevant sale, payout and end-of-term conditions. These details are agreement-specific, so don’t assume fees or outcomes.
For a fair comparison, capture the total amount payable and any stated costs of paying out the finance early. Confirm how the lender calculates those amounts and whether conditions apply. A hypothetical comparison can help organise your thinking, but it isn’t a real offer: only figures from current written terms show what applies to your purchase.
This checklist helps you assess vehicle finance solutions for new car buyers on more than the repayment shown in a quote. Keep the vehicle price basis and agreement details together, then compare each offer using the same assumptions.
Choose finance that fits your budget, trade-in and ownership plans
A sensible finance choice starts with the car you intend to buy and the amount you’re comfortable committing, not a repayment figure viewed on its own. Set a household budget that leaves room for running the car, then compare written finance terms and trade-in details against the same purchase plan. This keeps the decision practical, whether you expect to own the car for a few years or longer.
- Set your budget. Decide on an overall purchase limit and a repayment range that sits comfortably alongside your regular household commitments. Allow for ownership costs such as fuel or charging, servicing, tyres, insurance and registration, without relying on assumed averages.
- Shortlist a car and variant. Choose a vehicle that suits your needs and intended ownership period before comparing offers. A shortlist helps keep the purchase price and finance discussions focused on cars you’d genuinely consider. Private Fleet’s new-car buying service brings vehicle sourcing into the purchase process.
- Compare written terms. Review the amount financed, rate, fees, loan term and any final payment together. Consider whether the proposed term fits how long you expect to keep the car, and whether the repayments remain manageable over that period.
- Review your trade-in. Consider the trade-in value separately from the new-car price and finance offer. Then look at how including it changes the amount you would need to borrow, if it forms part of your purchase plan.
How should a deposit and trade-in affect the comparison?
A deposit or trade-in contribution may reduce the amount financed, but the effect depends on the purchase figures and agreement. Compare offers using the same deposit and trade-in assumptions. Assess the trade-in value separately from the new-car price, so each part of the transaction is clear. A trade-in doesn’t automatically improve finance terms or reduce borrowing in every arrangement.
Keep the term aligned with your plans. If you expect to change cars before the finance agreement ends, consider how the remaining balance and any early-payout conditions could affect that decision. If you plan to keep the vehicle longer, weigh the repayment schedule against the period you expect to own it. The agreement’s specific conditions matter, so read them before committing.
How can you keep the commitment manageable?
Test the proposed repayment against your budget after allowing for other household commitments and vehicle running costs. Think about whether your income or household needs could change during the term, and whether the agreement gives you the flexibility you want. This is a planning prompt, not personal financial advice. Comparing the car, trade-in and finance together can make the purchase easier to assess.
If you’d like help coordinating your new-car purchase and finance, share your preferred make or model, postcode and buying timeframe.
How Private Fleet brings car finance into a coordinated new-car purchase
Private Fleet can help bring vehicle sourcing, trade-in assistance and car finance into the same new-car buying conversation. This gives you a way to consider the vehicle you want alongside the practical steps involved in purchasing it, while keeping each offer and agreement clear for review.
What happens when finance is considered with the car purchase?
You can discuss your preferred make, model and variant, then consider the purchase offer, any trade-in and finance in context. Private Fleet sources vehicles rather than holding its own inventory. It is not a lender, manufacturer-owned business or authorised brand dealer; finance is provided under the relevant lender’s agreement.
The new-car buying service brings sourcing and purchase coordination together. As you consider your options, review the vehicle offer and finance agreement as separate parts of the decision. The car-buying process can help you understand how the purchase steps fit together.
What information helps move the enquiry forward?
Share your preferred make or model, postcode and buying timeframe to give the discussion a useful starting point. If you’ve narrowed your options to a shortlist or have a budget in mind, include that context too. You don’t need every detail finalised before outlining what you’re looking for.
It can also help to note whether you have a current car to trade in and what you want from the new vehicle. With those details in view, you can discuss the purchase and finance together while assessing written terms on their own merits. This keeps the focus on a car that suits your plans and a purchase you can evaluate with care.
Get help buying my new car
Take the next step with a clear plan
Before committing, give yourself a final checkpoint. Make sure the vehicle offer and finance agreement reflect the same car, variant and purchase details, and that the repayment schedule still fits your household budget. If anything has changed since you first compared offers, review the figures again rather than relying on an earlier estimate.
Use your preferred vehicle and intended ownership period as the starting point for a confident decision. The right vehicle finance solutions for new car buyers are the ones you can assess against the full purchase and your plans, without letting one appealing figure make the decision for you.
A considered next step can make the process feel more manageable. Bring your shortlist and buying timeframe into the conversation, and move forward at a pace that gives you room to understand the written terms.
Get help buying my new car
You’re ready to make your next decision with greater clarity and confidence.
Frequently Asked Questions
Can I arrange car finance before choosing my new car?
Yes, you can explore your borrowing capacity before settling on a particular vehicle, which may help narrow your shortlist. Treat any early indication as a starting point, not confirmation that a specific loan will be approved or remain available. Once you know the exact model and variant, revisit the application details and timing. Vehicle price, delivery arrangements and your circumstances can affect the final finance decision.
Is dealer finance always the easiest option for a new car?
No. It may be convenient to discuss finance where you’re buying the car, but the application and paperwork still need to suit your situation. Consider how much time you have to compare options, whether you prefer to handle the borrowing separately, and how the proposed finance fits the purchase timeline. Ease of arranging it is only one consideration, not proof that it’s the right option.
How much deposit should I put towards a new car?
There’s no universal deposit amount. Decide what you can contribute without leaving yourself short of funds for other priorities or unexpected expenses. A deposit can reduce the amount borrowed, but using more of your available cash may leave less flexibility elsewhere. Before settling on a figure, consider your broader finances and compare the resulting loan terms. This is general information, not personal financial advice.
Can I use my current car as a trade-in when arranging new-car finance?
Often, a current vehicle can be traded in as part of a new-car purchase. Before agreeing, check how the trade-in is valued, what condition assumptions apply and whether any amount owing on your current vehicle affects the transaction. Keep written records of the valuation and purchase terms. If the trade-in offer changes, ask for the revised figures so you can understand the effect on the overall deal.
Does a lower monthly repayment mean a better car finance deal?
No, not by itself. A repayment figure can be lower because the loan runs for longer, the payment schedule differs or a larger amount is due at the end. Check whether the quoted amount is weekly, fortnightly or monthly, and whether it includes all required payments. Comparing the cash flow across the agreement helps reveal whether the repayment pattern matches your income timing and budget.
What should I check before signing a new-car finance agreement?
Before signing, confirm that the contract names the correct borrower and vehicle, and that the agreed terms match the documents you’ve received. Check the payment dates, applicable conditions, optional add-ons and what happens if a payment is missed or circumstances change. Don’t sign with blank fields or unresolved changes. Keep a copy of the completed agreement and related documents for your records.
Can I sell or trade in a car that still has finance owing?
Possibly, but first find out from the lender what’s required to settle the existing agreement. Ask for the current payout figure and how long it remains valid, then compare it with the proposed sale or trade-in amount. If there’s a shortfall, plan how it will be paid before proceeding. Don’t transfer or sell the vehicle on the assumption that the outstanding finance will disappear automatically.
Does Private Fleet hold the cars it helps buyers source?
No. Private Fleet doesn’t hold its own vehicle inventory. For a buyer, this means the car is sourced through the purchase process rather than selected from stock owned by Private Fleet. The supplying dealership handles the vehicle’s sale and supply arrangements. Confirm the vehicle, variant and agreed purchase details in the relevant documents so you know precisely what is being ordered or purchased.